One of the most common questions after an accident is also one of the hardest to answer honestly: what is this actually worth? Most people either underestimate their claim significantly, assuming it only covers the medical bills sitting in front of them, or they overestimate it based on a number they heard from a friend’s unrelated case. Neither approach gets close to an accurate figure, because injury claims are not calculated with a single formula. They are built from several distinct categories, and the final number depends heavily on how well each one is documented and understood.
Here is a realistic breakdown of what actually goes into that number.
Medical Expenses Are the Foundation, Not the Whole Picture
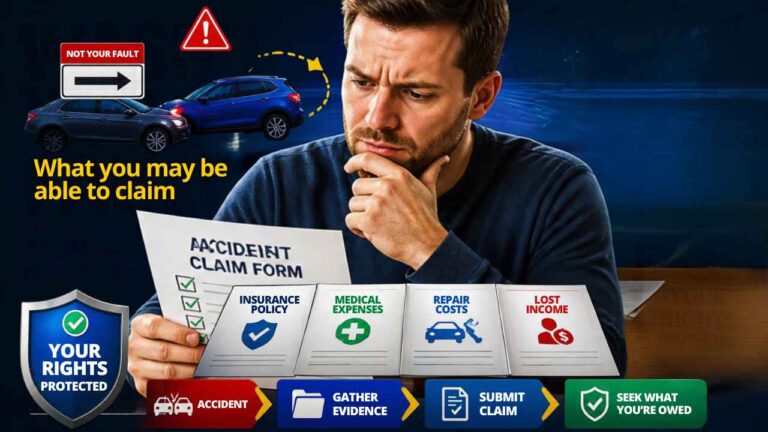
Every injury claim starts with medical costs, but the mistake many people make is treating this as the entire claim rather than just its foundation. Medical expenses include far more than the initial emergency treatment. Ongoing physical therapy, follow up specialist visits, prescription medications, medical equipment, and any future treatment your doctor anticipates you will need all factor into this category.
Future medical costs are frequently underestimated because they require someone to actually project forward, rather than simply adding up receipts that already exist. If your doctor indicates you will likely need additional treatment, another surgery, months of continued therapy, ongoing pain management, that projected cost belongs in your claim just as much as what you have already spent. Claims settled before this future cost is properly estimated routinely fall short of what the injury actually ends up costing over time.
Lost Income Extends Further Than Missed Paychecks
Lost wages seem straightforward on the surface, but the full scope is often larger than people initially calculate. This includes not just the days or weeks you were completely unable to work, but also any period where you returned at reduced hours, lighter duties, or lower pay due to your physical limitations.
For claims involving more serious or long term injuries, loss of future earning capacity becomes relevant as well. If your injury affects your ability to perform your specific job long term, or limits the types of work you can realistically pursue going forward, that reduced earning potential over the course of your career can represent a substantial portion of a claim’s actual value, far beyond what a few weeks of missed paychecks would suggest. This category is one of the most frequently overlooked, largely because it requires thinking beyond the immediate recovery period.
Pain and Suffering Is Real, But Notoriously Hard to Pin Down
This is the category that causes the most confusion, partly because there is no receipt or invoice to point to. Pain and suffering compensation accounts for the physical pain, emotional distress, and overall disruption to your quality of life caused by the injury, separate from the tangible financial costs.
Insurance companies often use internal formulas to estimate this, frequently based on some multiple of your medical expenses, but these initial calculations tend to favor a lower outcome for the insurer. The strength of this part of a claim often comes down to documentation that most people never think to keep, a personal record of how the injury affected daily life, sleep, relationships, hobbies, and mental health during recovery. Vague recollections months later carry far less weight than a contemporaneous account of what the recovery actually looked like.
The Severity and Permanence of the Injury Changes Everything
Not all injuries carry the same weight, even if the initial medical bills look similar. A soft tissue injury that fully resolves within a few months is valued very differently than an injury resulting in any degree of permanent impairment, chronic pain, or lasting limitation in function.
If your injury has any lasting effect, even a partial one, a formal evaluation to assess permanent impairment can significantly change the value of a claim, and this is a step many people never pursue simply because they are cleared to return to work and assume that means the case is closed. A permanent impairment rating, obtained through a proper medical evaluation once your condition has stabilized, adds an entirely separate dimension to a claim’s value that a purely short term view of the injury would miss entirely.
Fault and Comparative Responsibility Can Shrink the Number Significantly
Even a claim with strong documentation and serious injuries can be reduced substantially if any degree of fault is assigned to you. Many places apply a comparative fault standard, where your compensation is reduced proportionally based on the percentage of responsibility attributed to you, even if that percentage is relatively small.
This is one of the most common ways insurance companies work to lower a payout, by introducing even a modest, sometimes questionable, argument for shared fault. Understanding whether comparative fault applies in your situation, and being cautious about statements that could be used to support a fault argument against you, directly affects the real world value of your claim, independent of how strong the medical and financial documentation might otherwise be.
Why Early Settlement Offers Rarely Reflect True Value
Insurance companies frequently extend settlement offers relatively early in the process, often before the full scope of medical treatment, lost income, or long term impact is even clear. These offers are typically calculated using conservative assumptions and are presented at a point when accepting quickly can feel appealing, especially with bills accumulating.
The number that seems reasonable in the moment is often significantly lower than what a complete accounting, one that includes future medical costs, lost earning capacity, and a proper valuation of pain and suffering, would actually support. Once accepted, these settlements are almost always final, meaning there is no path to request more later if the injury turns out to be worse than initially understood.
How to Get a Realistic Number for Your Own Situation
Arriving at an accurate figure requires pulling together several pieces most people never organize in one place. Start with a complete accounting of medical expenses to date, along with a clear projection of anticipated future treatment based on your doctor’s guidance. Add a full calculation of lost income, including any reduced earning capacity going forward if the injury has lasting effects on your work.
From there, factor in the severity and permanency of the injury itself, ideally supported by a formal medical evaluation if any lasting impairment is possible. Consider whether any comparative fault issues might reduce the final number, and be honest about that possibility rather than assuming full liability will automatically rest with the other party. Finally, weigh the pain and suffering component based on documented impact to daily life, not a vague sense of how bad things felt.
This is rarely a simple math problem, and it is exactly why claims that are evaluated carefully, rather than settled quickly, tend to result in outcomes that actually reflect what the injury cost the person who lived through it.
The Bottom Line
An injury claim’s real value is almost never obvious from the medical bills alone, and it is rarely something either the injured person or the insurance company gets right on the first attempt without a careful, complete accounting. Medical costs, both current and future, lost income and earning capacity, the severity and permanence of the injury, and a genuine assessment of pain and suffering all combine to form the actual figure, and skipping any one of these categories almost always means settling for less than the injury genuinely cost. Before accepting any number, especially one offered early in the process, it is worth slowing down long enough to make sure every piece has actually been counted.